The global projector screen set market is entering a more divided phase, with low-cost, high-volume products competing on price while premium screens seek to justify higher prices through performance and integration features, according to a new analysis from IndexBox. The report examines the category from 2012 through 2025 and provides market scenarios extending to 2035.
IndexBox describes the market as developing a pronounced “barbell” structure. Basic screens are being supplied by private-label and value-oriented brands, while premium products are differentiated through features including ambient light rejection, acoustic transparency, flexible aspect ratios and compatibility with smart-home systems. Products positioned in the middle without a clear benefit are described as facing the greatest strategic pressure.
Premium screens compete on more than surface area
The report separates demand into several use cases: casual home entertainment, dedicated home cinema, gaming and portable professional applications. Each segment has different expectations around price, product capability and purchasing channel. That fragmentation moves the category beyond a simple replacement market in which screens are selected primarily by size.
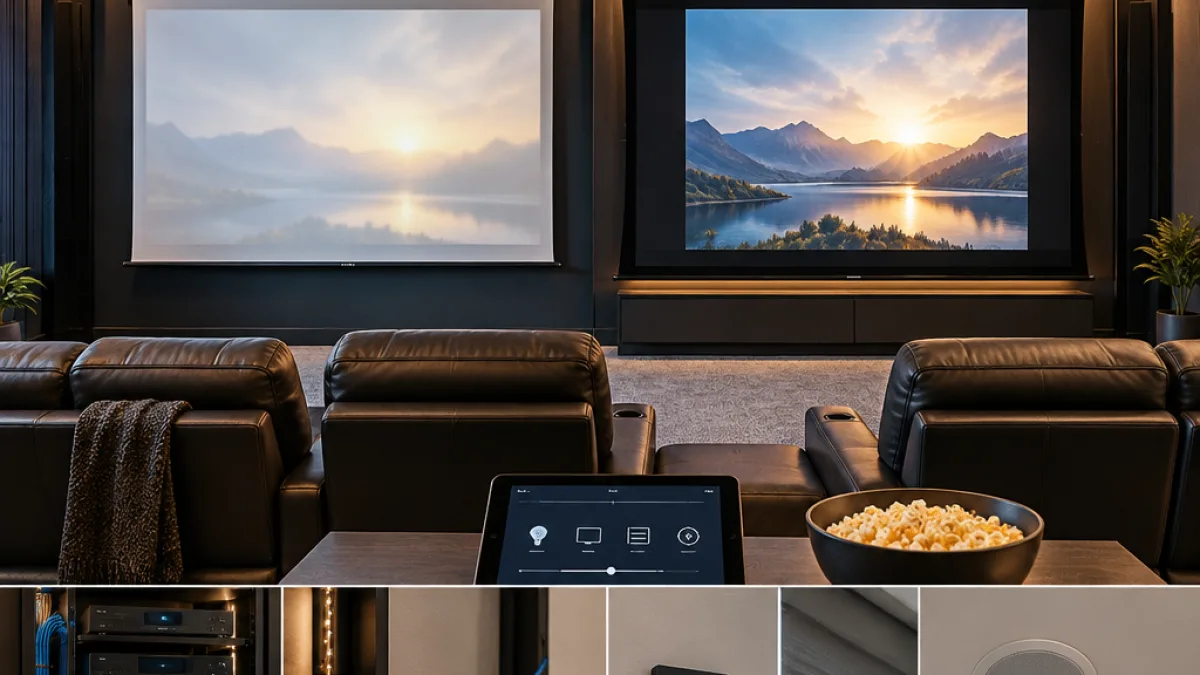
For custom theater projects, the analysis identifies benefit-led attributes as central to the premium segment’s positioning. These include screen materials designed to manage ambient light, surfaces that allow audio to pass through, multiple aspect-ratio options and integration with broader home control systems. IndexBox presents those characteristics as market differentiators rather than as uniform requirements across all applications.
| Market area | Characteristics identified by IndexBox |
|---|---|
| Value segment | Private-label and budget products, price competition and broad distribution |
| Premium segment | Ambient-light rejection, acoustic transparency, aspect-ratio flexibility and smart-home integration |
| Demand categories | Casual entertainment, dedicated cinema, gaming and portable professional use |
| Market outlook | Expansion through 2035, with profitability concentrated outside the commoditized middle |
Distribution is reshaping category economics
IndexBox says e-commerce, including large online marketplaces, has become the leading discovery and purchasing route for projector screens. The resulting price transparency increases pressure on manufacturers and distributors serving the entry-level category. At the same time, physical retail is being pushed toward demonstration-led selling and premium presentation environments rather than undifferentiated product display.
The report also points to a geographically diversified supply structure alongside substantial manufacturing capacity for basic models in concentrated production hubs. That combination supports aggressive pricing in the commodity portion of the market, while premium manufacturers rely more heavily on product benefits and application-specific positioning.
- Entry-level screens: high-volume competition is centered on price and distribution reach.
- Premium screens: manufacturers emphasize light management, acoustically transparent construction, format flexibility and integration.
- Channel shift: online marketplaces increase price visibility, while physical sellers are directed toward demonstrations and premium showcases.
IndexBox’s baseline outlook calls for continued global category expansion through 2035, although it expects volume growth in mature markets to remain modest and to depend substantially on replacement activity. The analysis says profitability will increasingly favor companies that establish a clear position at either the value or premium end of the market, rather than those competing in the increasingly compressed middle.